Payment pending settlement
Installment boleto keeps the status explicit while the first payment settles.
03 · Product Design case study
Casas Bahia Pay
A white-label BNPL product designed to make borrowing clearer before, during and after purchase.
My role
Senior Product Designer. Discovery, journeys, service blueprints, UI, prototyping, validation and delivery across digital and assisted-sales flows. In parallel, I lead internal adoption of AI-assisted Design workflows at Compass UOL.
The challenge
Credit should not feel like an opaque series of forms. People need to understand the offer, complete the agreement safely and know what happens next.
Assisted-sale phases at the POS, in layers: what the customer sees, what the associate does, what the partner systems record and what the credit engine runs behind the scenes.
| Layer | Phase 1Opening and data capture | Phase 2Simulation trigger | Phase 3Path and product | Phase 4Credit offer | Phase 5Application | Phase 6Voucher | Phase 7Till and payment |
|---|---|---|---|---|---|---|---|
| Physical evidence | Store counter and POS screen | Pre-approved badge on the associate screen | Shop floor and product screen | Payment options on screen | Identity validation screen | Voucher with a code on screen | Agreement PDF by email and receipt |
| Customer actions | Gives their ID number and what they are after | — | Picks the product and the purchase path | Decides between credit and other methods | Completes validation and accepts the terms | Receives credit confirmation | Pays at the till and gets receipt and agreement |
| Frontstage · associate | Opens the sale and captures the data in the system | Sees the pre-approval and plans the approach | Builds the offer together with the customer | Offers the credit line proactively | Guides validation and the agreement | Confirms the voucher and sends it to the till | Till redeems the voucher and hands over the receipt |
| Backstage · partner systems | Records the registration in the sales systems | Calls the credit engine | Builds the order | Shows credit as a payment method | Receives the application status | Links the voucher to the order | POS redeems the voucher and issues the receipt |
| Support · credit engine | Segments: already a credit product customer? | Soft simulation, with pre-approval reusable for seven days | Keeps the pre-approval valid | Prepares the offer with the product total | Validates identity and risk, and issues the agreement | Issues the voucher with amount, items and validity | Reconciles payment and activates the agreement, only once paid |
Public version of the artefact. Partner names, vendors and technical dependencies have been generalised.
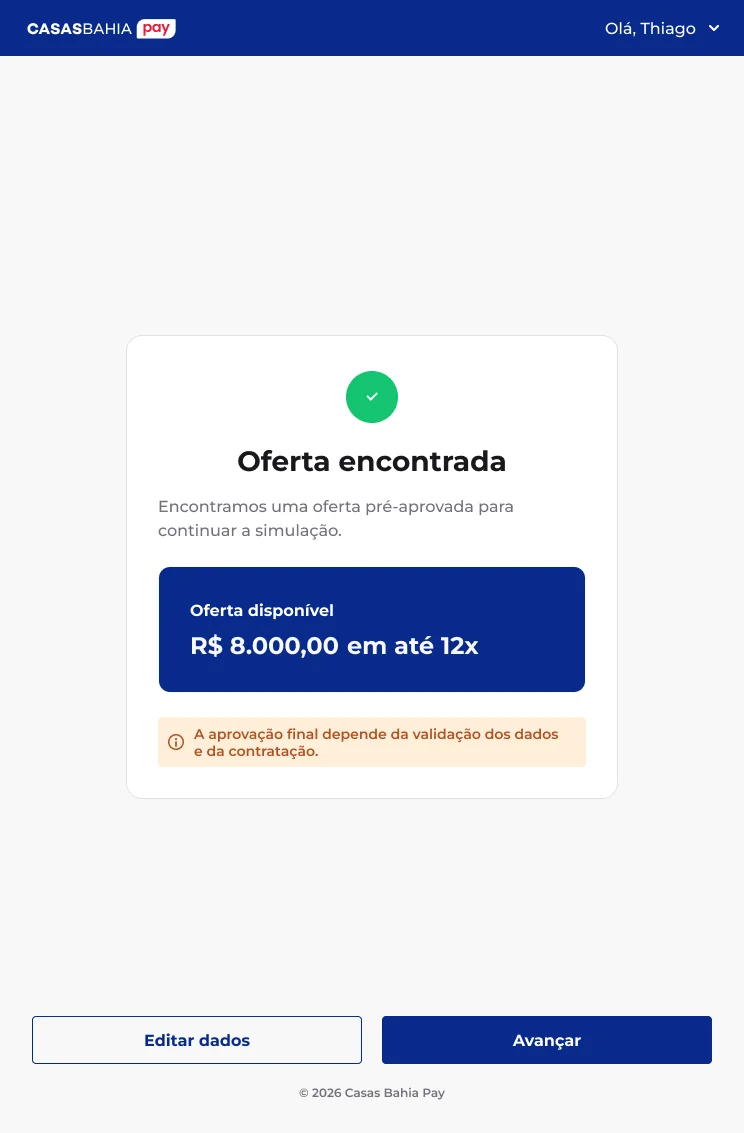
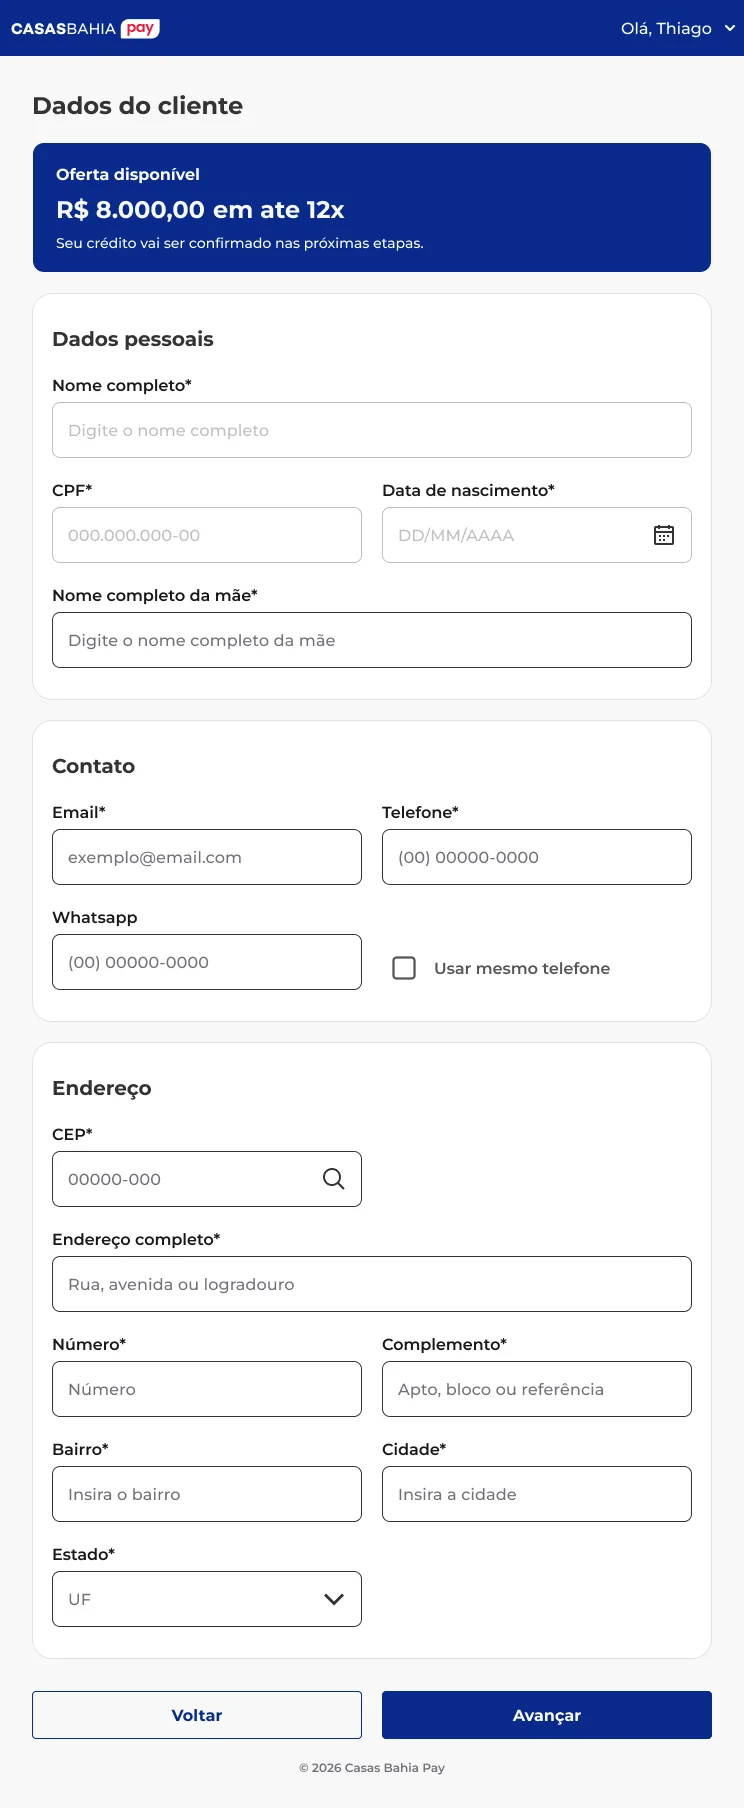
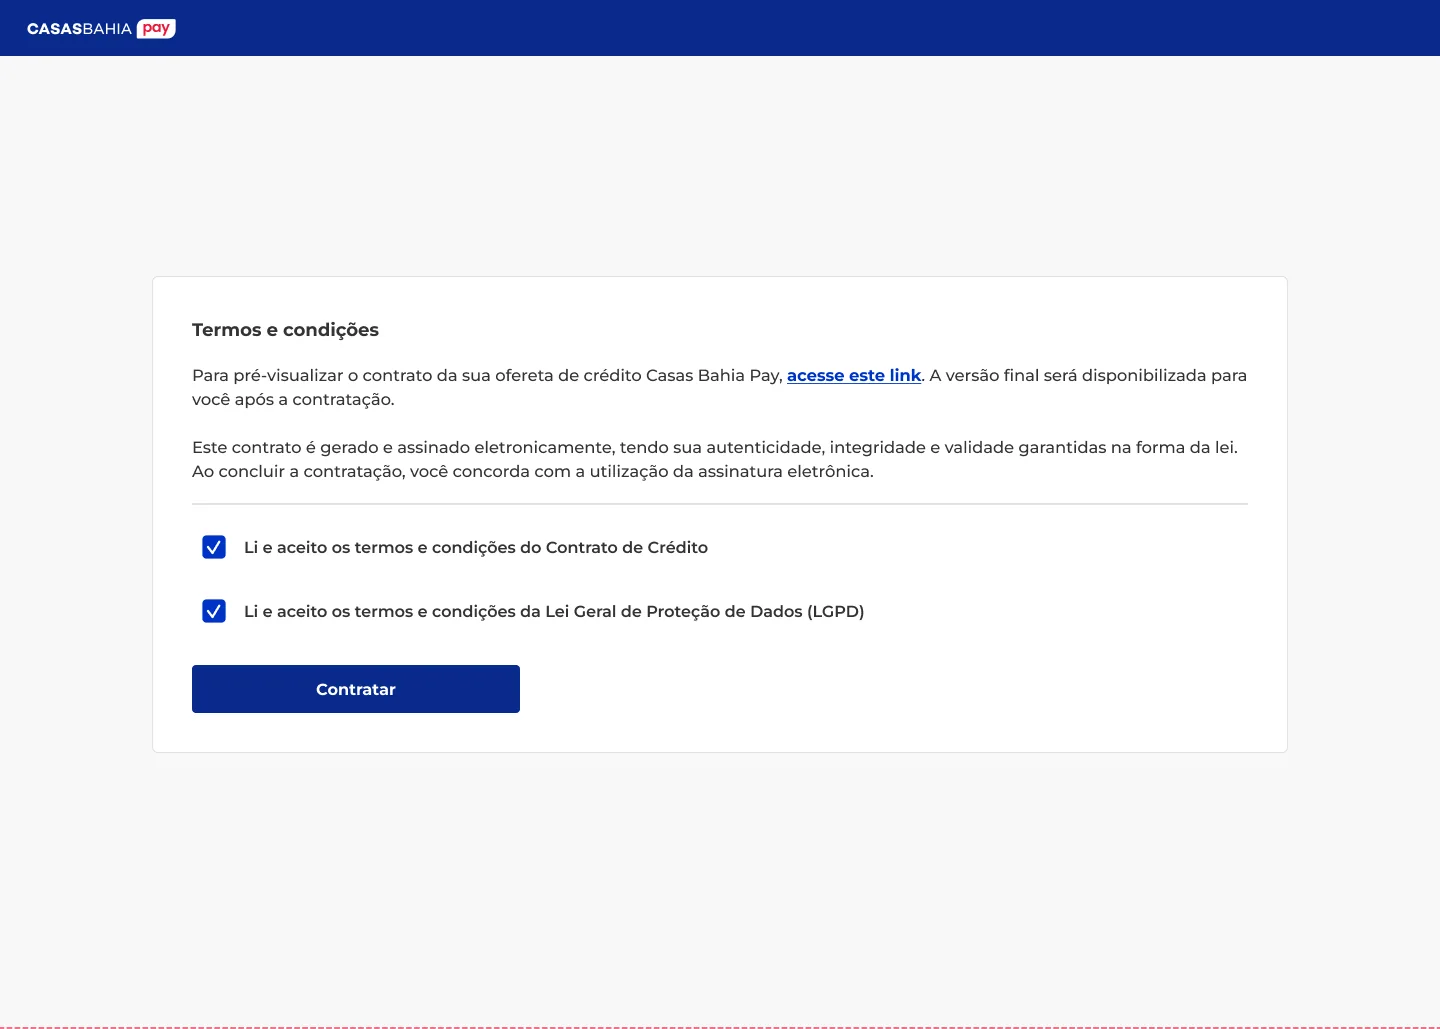
Product screens show simulation, offer, details, terms, security and agreement states.
Check eligibility without starting an unnecessary registration.
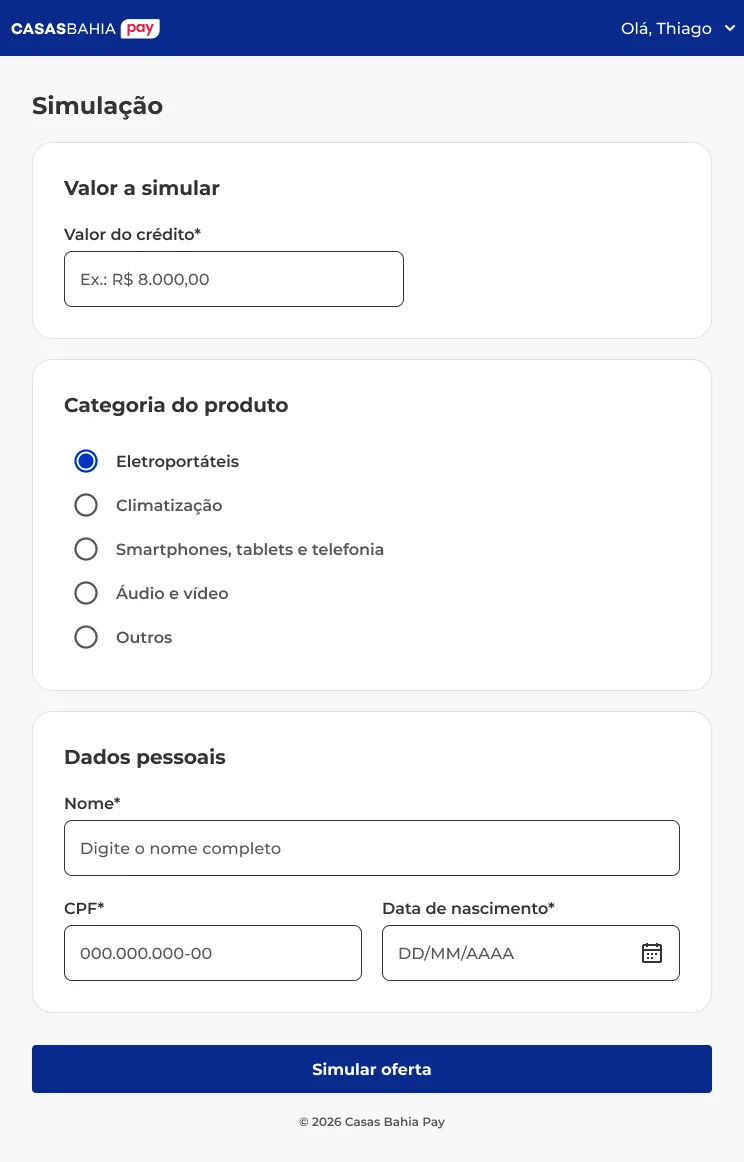
Explain limit, installments and conditions before asking for more data.
Collect only what is needed to move forward safely.
Make conditions and formalization easy to follow.
Handle identity and biometrics as a natural part of the journey.
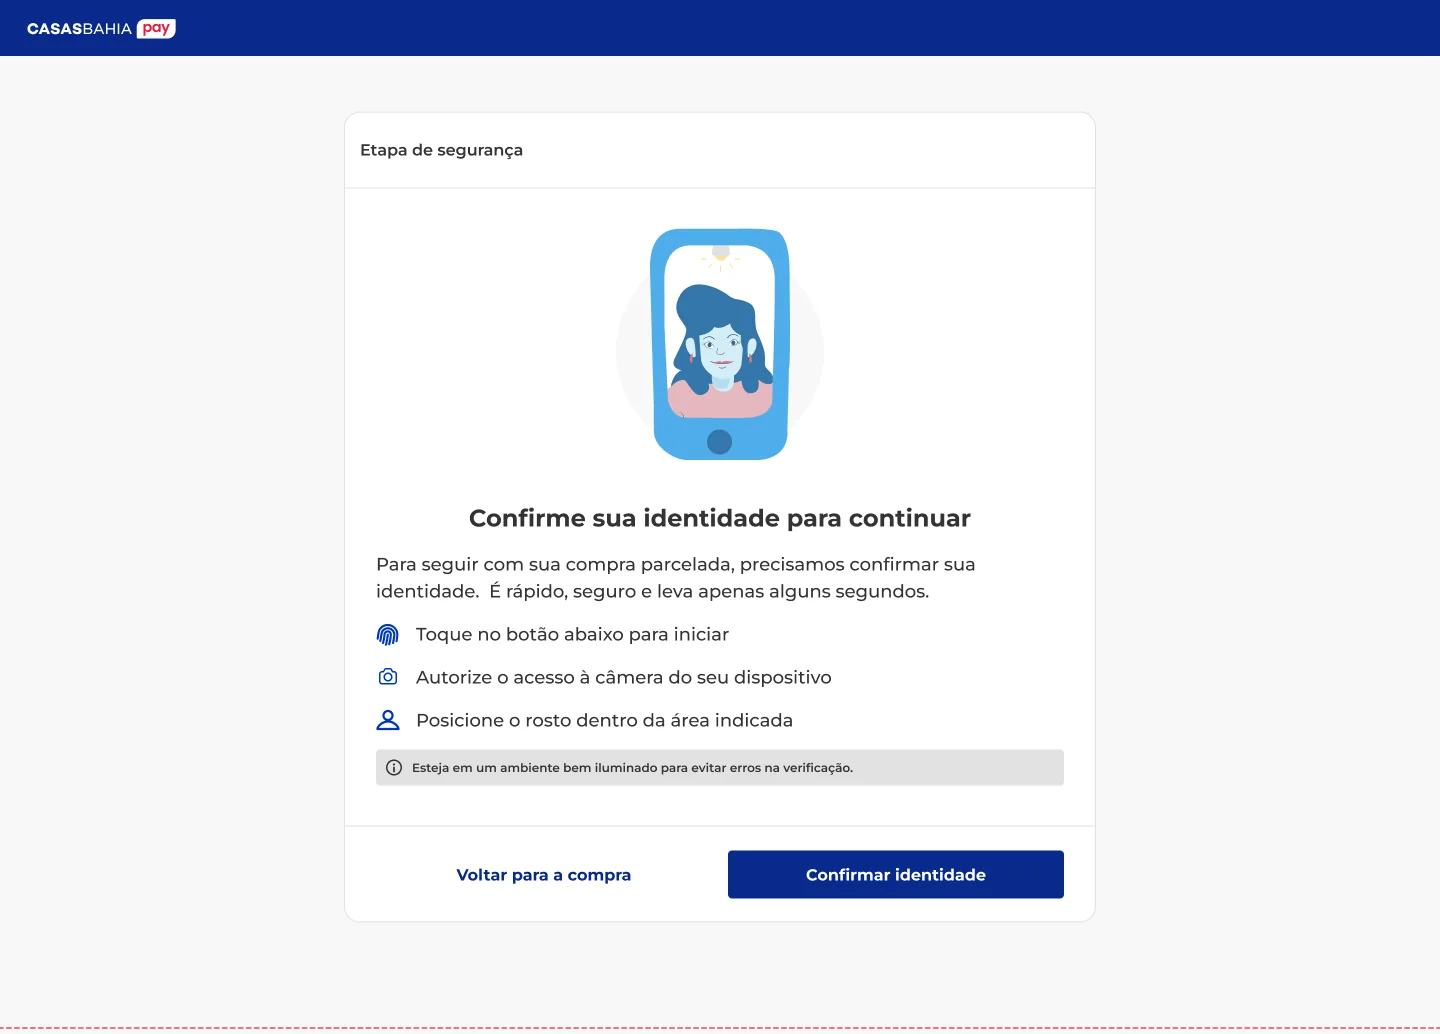
Confirm formalization and make the next step clear.
The project also documents payment pending settlement, a fallback validation route and credit reusable for up to seven days.
Installment boleto keeps the status explicit while the first payment settles.
When the main validation was unavailable, a secondary route let people finish on their phone and return to checkout, instead of dropping the whole application.
When credit is approved but the purchase is not completed, it can be reused for up to seven days.
The app comes in after the agreement is effective, reusing data and giving direct access to bills, a second copy and follow-up.
An account is only created or linked after the agreement is effective, reusing what was already given during the purchase.
Bills, a second copy and communications join the same experience instead of becoming another channel.
The same infrastructure needed to work in store for a retail partner and a telecom partner, with a straightforward path for associate, customer and checkout.
Each one covers a different moment of the purchase.
Part of the amount is paid instantly by Pix and the rest is financed on the approved credit.
Instalments become boletos, for people who cannot or prefer not to use a card.
The merchant is paid in full up front while the customer pays in instalments, with no boleto in between.
The actual reach of what was designed, from digital checkout to the store till.
Available for opportunities
I am looking for teams that treat design as part of product decisions, and companies that need to turn complex problems into better digital products, experiences or operations.